 Skip to content
Last Updated: November 3, 2026
Quick Summary
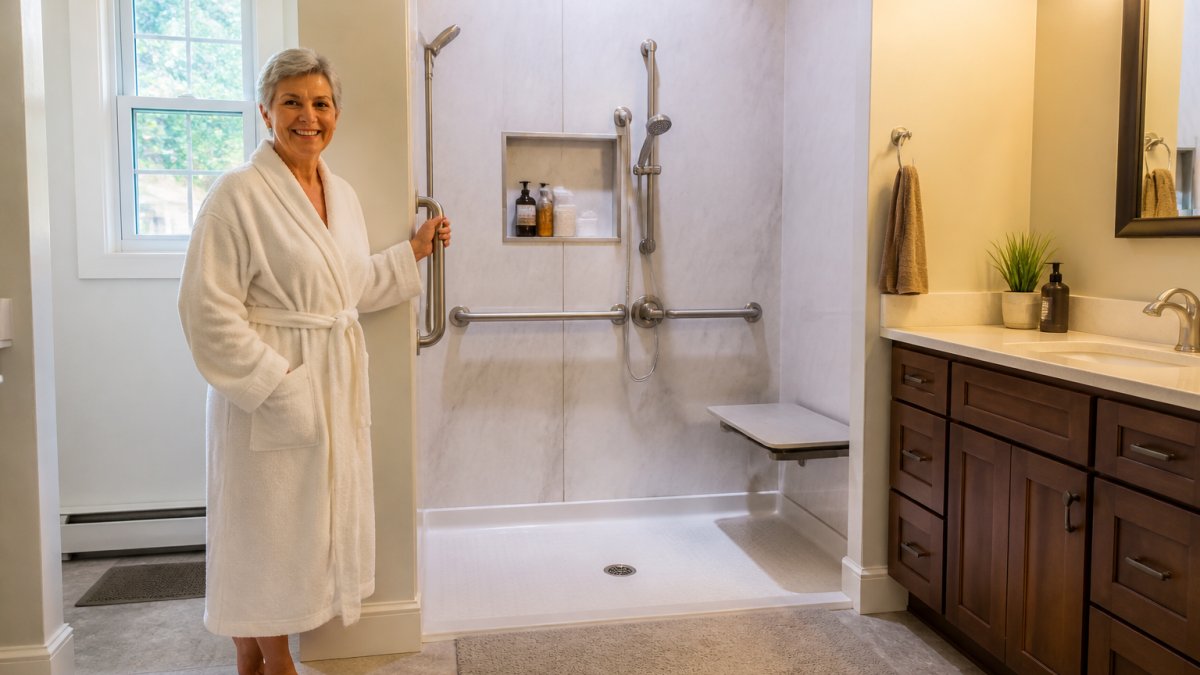
No, most health insurance plans do not pay for barrier free showers outright. Original Medicare treats a shower conversion as home modification, not covered medical equipment. Some Medicare Advantage plans, Medicaid waivers, and private policies bend further, but you have to ask the right questions before you swing a hammer.
- Original Medicare covers medically necessary equipment and certain home health services, not remodeling labor.
- Medicaid home and community-based waivers are the most likely path to funding an actual modification.
- Get a physician’s letter of medical necessity tied to a specific functional limitation before work begins.
- File equipment appeals and construction appeals separately, because they argue different questions.
- Homeowners insurance generally covers sudden damage, not accessibility upgrades.
Table of Contents
- The Short Answer on Barrier Free Showers and Insurance
- Medicare Coverage for Accessible Bathroom Modifications
- Documentation for Insurance Coverage of Bathroom Modifications
- How to Appeal an Insurance Denial for Home Modifications
- Private Insurance, Homeowners Policies, and What They Really Pay For
- Costs, Exclusions, and Alternative Funding Sources
- Pros and Cons of Pursuing Insurance for a Barrier Free Shower
- Get a Free Buying Review Before You File a Claim
- Frequently Asked Questions
The Short Answer on Barrier Free Showers and Insurance
No, most health insurance plans do not pay for barrier free showers outright. Original Medicare treats a shower conversion as home modification, not covered medical equipment. Some Medicare Advantage plans, Medicaid waivers, and private policies bend further, but you have to ask the right questions before you swing a hammer.
I’m George Bentley. I founded Bentley Baths in 2003 after my own mother’s bathtub accident, and I’ve spent two decades helping families sort real coverage from sales talk. Here’s the uncomfortable truth most contractors won’t tell you: the shower itself is rarely the covered item. The medical need behind it sometimes is.
So what does that mean for your wallet? It means you need a paper trail before you need a plumber. Below, I’ll walk you through exactly which payers cover what, how to document a medical necessity claim, and how to appeal when the first answer is no.
What Insurers Usually Cover and What They Reject
Insurers draw a hard line between equipment and construction. A shower chair, a grab bar, or a handheld showerhead may qualify as durable medical equipment or a covered home health item under some plans. Tearing out a tub and rebuilding a zero-threshold entry usually does not.
The Medicare.gov guidance on durable medical equipment is a good starting point because it defines what counts as covered equipment. Construction is a different animal.
- Often covered, with a prescription: shower chairs, transfer benches, commodes, some grab bars
- Sometimes covered through waivers: accessibility modifications tied to a documented need
- Rarely covered by Original Medicare: the remodel itself, waterproofing, drainage, labor
- Almost never covered: cosmetic upgrades bundled into the project
Watch out: some contractors blur “covered equipment” and “covered construction” to make a sale sound easier. They are not the same claim, and mixing them can sink your whole request.
Medicare Coverage for Accessible Bathroom Modifications
Original Medicare does not cover home modifications like a barrier free shower. It covers medically necessary equipment and certain home health services, not the remodeling labor that makes a bathroom accessible. Medicare Advantage plans can offer extra benefits, and some do.
This is where families get confused, so let me be blunt. You may hear “Medicare pays for that” from a salesman. Ask him to show you the plan document. If he can’t, he’s guessing.
For a deeper breakdown of what the walk-in tub side of this looks like, our guide on whether Medicare pays for walk-in tubs covers the coverage question in more detail.
Original Medicare, Medicare Advantage, and Medicaid Waivers
Three different payers, three different rules. Original Medicare is the strictest. Medicare Advantage is a private plan that must cover what Medicare covers but may add supplemental benefits, and those extras vary by plan and year. Medicaid home and community-based waivers are the most likely path to funding an actual modification, but availability depends on your state and whether you qualify.
- Original Medicare: equipment yes, construction generally no
- Medicare Advantage: check the plan’s supplemental benefit list each year
- Medicaid waivers: state-specific, often the best shot for a real remodel
- VA benefits: worth asking about if you or your spouse served
The Medicaid.gov page on home and community-based services explains how waivers work. Read it before you assume you’re eligible.
Documentation for Insurance Coverage of Bathroom Modifications
Documentation wins or loses these claims. A letter from your doctor describing a medical necessity, tied to a specific functional limitation, carries far more weight than a receipt. Get it in writing before work begins.
Here’s what a strong file looks like:
- A prescription or letter of medical necessity from your physician
- A description of your functional limits, such as trouble stepping over a tub wall
- An assessment from an occupational therapist or qualified professional
- Photos of the current bathroom and the specific hazard
- A written estimate that separates equipment from construction
- The payer’s own prior authorization form, filled out completely
An in-home safety assessment can generate much of this proof. If you want to see how that works, you can book an in-home bathroom safety assessment and use the findings as supporting documentation.
How to Appeal an Insurance Denial for Home Modifications
A denial is not the end. It is the opening move, and most denials I see cite one of two things: “not medically necessary” or “not a covered benefit.” Both can be challenged, but only with the right paperwork filed in the right order.
- Read the denial letter line by line. Note the exact reason code, the appeal address, and the deadline. Write those three things on a sticky note and put it where you will see it. Deadlines are strict and they do not care about your vacation.
- Request the plan’s full appeal procedure in writing, including the internal appeal and external review timelines. Ask for the specific clinical criteria the plan used to deny you. Plans are generally required to provide this on request.
- Ask your physician to write a letter that answers the exact reason cited, not a general letter about your condition. If the denial says “not medically necessary,” the letter should tie the shower modification to a documented functional limitation and a safety risk. If it says “not a covered benefit,” the letter should address whether the item qualifies as durable medical equipment or a home health item under the plan document.
- Submit a written internal appeal with the full documentation file: the prescription or letter of medical necessity, the occupational therapy assessment, photos of the hazard, and an itemized estimate that separates equipment from construction. Send it with a trackable method and keep the receipt.
- Track every deadline. Internal appeals typically have a defined response window, and if the plan misses it, that can strengthen your position. Keep a simple log of dates, names, and reference numbers.
- If the internal appeal fails, request an external review. The USA.gov guide to appealing health plan decisions explains the external review option and the timelines that apply. External review is where an independent reviewer looks at the plan’s decision, and it is often the step families skip because they are tired.
Watch out: the most common mistake is filing an appeal that argues emotion instead of criteria. The reviewer does not know your mother. The reviewer knows the plan document and the clinical criteria. Write for that person.
One more distinction that matters: a denial for a shower chair or a transfer bench is a different appeal than a denial for the construction of a zero-threshold shower.
If you are staring at a denial letter right now and the deadline is close, do not wait to book anything with me. Call your plan’s member services line, ask for the appeal fax number and the deadline in writing, and start the paper trail today.
Private Insurance, Homeowners Policies, and What They Really Pay For
Private health plans follow the same equipment-versus-construction split, but some are more flexible than Medicare. Homeowners insurance is a different story: it generally covers sudden damage, not accessibility upgrades. Don’t expect your homeowner policy to fund a remodel unless a covered peril caused the need.
What most guides miss is that the answer depends on your specific plan document, not on a general rule. Two neighbors with the same insurer can get different answers because their plans differ.
- Private health plans: ask about DME and home modification riders
- Homeowners insurance: covers damage, not upgrades
- Long-term care policies: some include home modification benefits
- Employer flexible spending accounts: sometimes usable for qualifying equipment
Costs, Exclusions, and Alternative Funding Sources
Budget honestly before you file anything. Even a partial approval leaves you paying the construction side, and that’s the larger number. For a clear look at what the shower itself runs when you’re paying out of pocket, our breakdown of barrier free shower cost with installation walks through the real numbers.
Alternative funding worth exploring:
- State Medicaid waiver programs
- VA home modification grants for eligible veterans
- Local Area Agencies on Aging
- Nonprofit and community assistance programs
- Manufacturer or contractor financing, read the terms carefully
Watch out: financing that sounds painless can carry high rates and long terms. Read the fine print before you sign anything.
Pros and Cons of Pursuing Insurance for a Barrier Free Shower
Chasing coverage has real upsides and real headaches. Here’s the honest balance.
| Factor | Pros | Cons |
|---|---|---|
| Cost | May offset equipment or modification costs | Construction often excluded |
| Time | Forces a documented medical need | Appeals can take months |
| Paperwork | Creates a clear record | Requires doctor and therapist involvement |
| Outcome | Can unlock waiver funding | Approval is never guaranteed |
Best for: families with a documented medical need and a flexible timeline.
Skip if: you need the bathroom usable this month and can’t wait on an appeal.
Get a Free Buying Review Before You File a Claim
Before you file a single form, get a second set of eyes on the plan. A Free Walk-In Tub Buying Review With George walks through your options, your documentation, and the questions to ask your insurer so you don’t waste a claim on the wrong item.
At Bentley Baths, we offer free in-home and virtual evaluations by age-in-place specialists. We can identify the specific hazards in your bathroom and help you build the documentation a payer will actually read. If you’re also considering a remodel, you can receive a free consult on a bathroom remodel that pairs with the coverage review.
Weighing a roll-in shower against a walk-in tub? Our comparison of roll-in shower vs walk-in tub helps you decide which solution fits your needs before you commit.
Frequently Asked Questions
Are barrier free showers covered by insurance?
Rarely by standard private policies, which usually treat a barrier free shower as a home improvement rather than a medical expense. Medicare generally excludes home modifications, though some Medicare Advantage plans may offer limited flexibility. Medicaid home and community-based waivers are the most realistic path, and they vary by state. The key is proving medical necessity with a prescription and documentation. Ask your plan in writing before you sign a contract.
Does Medicare pay for a barrier-free shower?
Original Medicare generally does not pay for bathroom modifications, including barrier-free showers, because they are considered structural home improvements. Some Medicare Advantage plans offer supplemental benefits that may help with certain home safety items, so check your plan’s evidence of coverage. Durable medical equipment coverage is separate and does not usually extend to construction. Get any approval in writing before work begins.
What documentation might an insurer request for a barrier-free shower?
Expect a prescription or letter of medical necessity from your physician, a description of your mobility limitations and diagnosis, an occupational therapist assessment, a detailed written estimate that separates equipment from construction, and photos of your current bathroom. Insurers may also ask for prior authorization. Keep copies of everything you send and note the date. Missing documentation is the most common reason claims stall.
How can I appeal an insurance denial for a bathroom modification?
Read the denial letter carefully and note the deadline and the specific reason given. Request the plan’s internal appeal process in writing, include your physician’s letter of medical necessity, and address each reason point by point. If the internal appeal fails, ask about an external review. Keep every document and send appeals by trackable mail. Deadlines are strict, so act as soon as the denial arrives.
Insurance rarely covers the whole project, but the right paperwork can move the needle. If you’re tired of guessing which payer covers what, get started with Bentley Baths and schedule your free evaluation today. Call 800-688-0055 or visit BentleyBaths.com.


